Monday, December 31, 2018

Review 2018

Been almost a year since i last blogged, been, last post being 2017 and financially, my last update was at 2016 review.

My portfolio was a huge $2,130 at 31 December 2016 and I had committed to set aside $300 a month on investments.

Almost 2 years on, how have i progressed with my savings?


As at year end, my portfolio is at $14,510, which is not bad! considering i started at $2,130 in 2016. Honestly though i added most of my positions in the last 2 months when the prices of the equities started coming down. My cash holdings is around 2k as of now, and going to add more as i get my paycheck.

Point is, i managed to set aside more than my aim of $300 a month (otherwise, i would only have $7,200 by now + equity gains/losses)

Did not specifically track dividend income from the counters, but given the (huge) size of the portfolio, it is likely to be immaterial.

In any case, because i am using Standard Chartered online trading platform, all dividends would be automatically credited into my securities trading settlement account for reinvestment.

Shall continue to set aside my own savings and periodically use it to build up my ETF position, because currently that's mostly all (as above) i am holding onto now.

Long long way to FIRE.

Friday, December 1, 2017

General updates

Wow, been sometime since i blogged. Lots of things happening in real life that got me sidelined from blogging.

Addition to the family:
Welcomed my daughter to the family in November. A bundle of joy. To make this post remotely finance-related, i shall classify her as a 21 year endowment plan. Returns on investment, unknown, and no projection available as well.

Cost of investment: Very high.

I think it's not an investment you will go into based on the numbers alone. I mean, the initial outlay into this is quiteeee high.

Giving a rough breakdown of the costs associated, and i give only approximate figures here:

(1) Regular gynae check-ups: 250- 350 a visit. Roughly 12 visits (monthly, then moving to shorter intervals as the due date approaches)

Total for check ups: $3,600

(2) Miscellaneous medical costs associated: Pre-natal check-ups. There used to be an oscar test to test for Down Syndrome, which costs about $300-500 and have a 75% accuracy ration, we decided to go for the Harmony test. It costs $1,500, but have 99% accuracy reading. That plus other supplements/tests/scans that needs to be undertaken.

Total miscellaneous medical: $2,000

(3) Nursery room: Outfitting a room for the new member costs money. Baby cots, dressers, clothes, strollers. These things do not come cheap

Total for nursery: $5,000

(4) Food expenses/supplements: Grocery bills went up. Went marketing every week to buy cod fish for the wife to eat. And that is like.... premium. Bird's nest, Chicken Essence become par for the norm. I did not track this expense though.

(5) Cost of delivery: Went for delivery at a private hospital (Thomson Medical). Apparently it is one of the more affordable private hospital compared to the others. Cost of delivery varies depending on the complexity of the procedure, i.e., if you are going for a caesarean operation, normal delivery, with or without epidural (anesthetist required)

Total for delivery: $9,000*

*Note: Medisave could be used to help defray the costs up to $3,000 for normal deliveries. More could be used for Caesarean-section deliveries.

You would have noted that i did not exactly scrimp and went for the lowest cost option. Decision was not made on cost as i think being pregnant is not easy, and paying (quite a bit more) for comfort would help go a long way to making the process for the wife much better.

There are ways to save on this: going to a public hospital (delivery and gynae check up costs would be much lower), but weighing between the 2 i consciously went for the more expensive option. Sure, it could have helped purchase a few lots of STI ETFs perhaps... maybe 20 years later i would rue the choice, but i guess some decisions have to be made.

So what's the total cost i incurred for this 'investment'?

A whooping $19,600.

And going forward, there would be monthly 'cost averaging into this', and who knows the potential payout 21 years later?

Economically, i think the maths don't work out. ;)

To balance this out a little, the government does help out a little.

(1) Baby Bonus: $8,000 for the first born, spread over several tranches disbursed
(2) Child Development Account - $3,000 first step incentive into the child's account, plus up to another $3,000 dollar for dollar matching

There are tax incentives given for parents with babies, which will help out a little

Saturday, January 14, 2017

Income Review 2016

Not many streams of income left in 2016 that will bring me into 2017, having liquidate most of my positions to purchase a second home.

Passive income:

As can be seen... my passive income dropped from 2016 as compared to previous years. Liquidated most of my assets to get another house which i am currently staying in. So it will be like a fresh start in 2017 when i try to build up my portfolio again to get income from dividends. Meanwhile, also hoping that the rental from my HDB will add a much needed boost to my passive stream.

Been holding cash a bit the past few years to buy another house, I guess that's why my dividends income wasn't that significant anyway.

Also only managed to get 1 month of rental out of my flat, and i net the agent's commission off. My US apartment continues to generate income, although there seems to be en-bloc interest in that. Let's see if i am forced to sell out, which is not ideal as i kind of like the regular USD income stream.


Portfolio as at 31 December 2016:
A grand total of $2,130. Now that I do not expect to use huge amounts of cash anymore in the near future, I am more comfortable in placing more into equities. Although the current amount i am placing now is still $300 a month. I should be looking to increase the amount in 2017. Waiting for my expenses situation to stabilize further, and to build up a bigger financial buffer too.


Monday, January 9, 2017

Expenses Review 2016

That time of the year when i look back at my expenses in 2016... and see how much better or worst did i fare financially...

I really only started tracking my expenses in 2015 when i got YNAB, and my first year expenses were recorded in 2015 expenses review.

It was pretty interesting to see where my money went to. I guess it would be even more interesting (for me that is) to see where i stack compared to last year.

Car Expenses: $31,687.88 (2015: $33,198.99)
Pretty consistent here. The slight disparity was because I did without a car for slightly under a month where i sold off my fancy ride to get a more down-to-earth vehicle. I expect the expenses in this category to drop in 2017.

Fixed Expenses: $17,792.31 (2015: $14,234.21)
This category is getting higher, and boils down to me increasing my insurance cover as described in here. Also taxation is higher (if i recall, there is a 1-off relief previous year) due to slightly higher income. An area which i can manage better, with SRS, topping up with CPF perhaps. I have been putting this off because I kept some cash on hand to fund my home. Now that that is out of the way, I can look to reducing some income tax expenses.

Monthly Bills: $2,322.48 (2015: $2,943.24)
Phone bills, gym membership. Slightly lower this year, as I managed to get reimbursement for my gym fees late last year as part of corporate benefit. Also my phone bills gets transferred to my 'family account' as part of a total package from Singtel. So likely i will drop this category in 2017.

Daily Expenses: $7,566.51 (2015: $9,081.47)
Total family expenses goes here (food, entertainment etc). Went down due to a conscious effort to cook more at home. Although in the grand scheme of things - it didn't look like it helped much. Maybe savings of $100 a month.

Holidays: $2,839.81 (2015: $8,239.05)
Too busy to take a break - a good thing for the wallet!

Personal Expenses: $6,538.75 (2015: $6,175.5)
Somewhat similar to last year. Was higher this year because i cabbed everywhere when I was without a car. Surprising to me though - because I thought I DID try to watch my spending on other areas like office meals and social entertainment expenses.

Bringing me to a total of $68,747.74 (2015: $73,872.46)
So, after a year of belt tightening, I cut my expenses down by $5,000 p.a. Which is about $600 a month.

Total essential expenses would be $43,897.57 [$31,897.57+$12,000 family expenses] (2005: $42,140.98)

And the daily maintenance expenses would be $3,500. Approximately same as last year as well. Having said that though, I still need to factor in the mortgage of my new house. So in reality, the figure per month is higher.

Overall, I think it is quite surprising to me. Looks like the efforts I have put into cutting my expenses did not bear as much fruits as I thought it should. It certainly felt like I put in more effort than satisfaction I get in the return for the savings!

Saturday, December 24, 2016

Transactions in December + hitching

Coming to the end of the year, where did 2016 go to?

Did my regular savings plan of 300 bucks a month, and this month, i decided to get some bonds instead. So i purchased A35 at $1.141. I had left overs from my previous purchases of STI ETFs, so even though the total purchase amount is $343, I had enough to cover the transaction amount.

 Bonds are less volatile... good for people who are getting old like me. I used to be 100% in equities, but some diversity couldn't hurt!

I envisage that as I progress with more savings, I would slowly increase my bond component. At the moment, I'm happy to let it be at around 10-20%.

Also, i am looking forward to collecting more dividends next month. A grand amount of $24.54. Since I restarted my portfolio less than half a year ago, with $300 a month, i am happy that the dividends can last me for a week's lunch. Although that is only hypothetical as I would not be spending it, but going to reinvest it eventually with my regular RSP.


Grabhitch:
From my previous posts, you would know that I sold my flashy 2 door car, and downgraded to a more modest 4 door vehicle. My previous vehicle wasn't approved by Uber because it is a 2 door (and they can only allow 4 door). With my new ride (yes, i know it is still a luxury item), I can sort of monetize the liability a little. Now when i go out and if my company wants to get a taxi, i get him/her to call for a hitch driver (and I will accept the booking). Grab pays incentive for hitch drivers, and i would be the beneficiary of it. :)


And, not forgetting to wish you and your family, a very Merry and Blessed Christmas, and a happy new year ahead!


Friday, November 25, 2016

Transactions, happenings Oct/Nov 2016

Didn't blog for 2 months, was kinda busy. Did my monthly purchase of 100 units of either G3B or ES3.
Guess 100 units work nicely based on savings of $300 a month.


Other significant updates:

(1) Finally secured a tenant for my HDB - market is indeed softening... the house sat empty for 1 month. While logically I know there is definitely a vacancy period, I can't help but feel that every day the house sits empty, I am losing money. All is good now though - the rental deposit is now in my bank account. Ka Ching!
Rates have come down slightly - but still not too bad for a stream of rental income.

(2) Sold my flashy car... after listing it on consignment for 1 year... there is finally a taker. Love that car - especially the cool breeze at night when you drive top down. But after 5 good years, i think it was time to let go... Uber didn't even accept my car as it was a 2 door ride... (back when i was thinking of getting extra cash). In case you think i am being extra financially prudent by selling the car and taking public transport, i have to admit, i am not. I just downgraded to a bread and butter car. It is indeed very tough (i am very pampered) after driving for close to a decade to get back to BMW (bus mrt walk) - doing it for a few weeks now, and actually Uber is quite okay, if there are promotions going on.

So, i guess it is a compromise between wanting to save more money and still have a car around... i know it delays retirement by a couple of years, but it is indeed a conscious decision.a

Wednesday, September 28, 2016

Transactions for Sept '16 + accidental lifehack

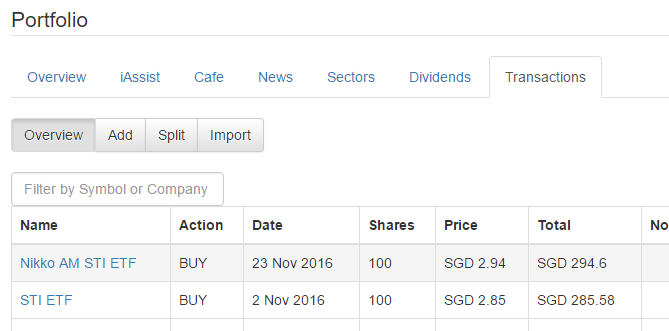
Continued my DCA into the STI index. Another 100 shares for the month. Using the transactions capture from SGXcafe. :)


Incidentally, i chanced upon an accidental life hack from for a small amount of free cash flow. So i signed up for an insurance policy using the OCBC Cashflo card which breaks any purchases into monthly installments. And then because another policy came up which i preferred.... i freelooked the old policy (and got the cash refund from the insurance company in 1 lump sum).

End result - i got interest free installment from the insurance company. It wasn't my intention, but it is indeed an accidental life hack for a small amount of cash flow.

Sunday, September 11, 2016

Insurance Review

Been busy recently trying to renovate my house.... costs of renovation is definitely way different from what i remember when i did up my house 8-9 years ago! My curtains and lights are double of what i spent previously. Although regrettably my record keeping the last time has been far from ideal, so wasn't able to do up a very comparison.

Any how.... due to the taking on of additional liabilities (and with getting older), decided to do an insurance review. I guess with age, one feels more afraid, with more things to lose... hence unwilling to take on risks which I can pass off to others.

Hospitalization and Surgical:
With the launch of AXA shield plans, i think it is currently one of the best shield plans around, with the highest annual policy limit (1 million per year), and longest pre and post hospitalization benefits. Meaning, one can claim for certain hospitalization visits after 365 days from discharge. I am currently with Aviva, and may be switching to AXA while i am healthy and still able to switch.

Critical illness:
I have Great Eastern's critical illness plan at the moment, but was quoted a similar one for AIA but at close to $1k cheaper per annum. The differences are, to me marketing tactics by GE to charge a premium.
 - For example, a shorter survival period of 7 days compared to 30 days. If one were to come down with a CI and passes away within 7 days... the CI will not pay out, true.

However, the purpose of CI is to help defray the costs of medication/differences in lifestyle after being diagnosed. If one were to die within 7 days, then the purpose of CI payout will not be required. The death benefit from my term life would pay out. The argument is that the premiums paid for CI policy would be 'wasted'. However, that's the purpose of buying insurance - i always treat it as an expense. People don't like to see wastage, and hence the sales of 'life policies' where you get what you paid for your premiums back is always higher. People fail to realize that a life policy is just a bundle of 'wastages + lending the insurance co to invest for you and return it back to you at a low rate of return'.

Death Benefit/TPD:
Increased it quite significantly, given the taking on of additional liabilities. IF something happens to me, i would not want my family to be saddled with a huge mortgage. The term life policy comes with TPD, so I am covered for that as well.

I got this instead of a reducing balance policy as i think the difference in price is not that material, and if i have additional obligations in the future, i would need to top up my coverage next time anyway.

Disability Income:
I added this as this is part of the holistic insurance package review. I feel that we should look at insurance needs as part of a holistic strategy... and this was how i viewed it. If i fall sick and needs to be warded, my H&S would kick in and pay for the bills. But if i cannot work due to the sickness, this disability income will kick in and pay for my monthly expenses (and mortgage).
If it is due to CI, i will be able to use the CI lump sum to pay for whatever bills that the H&S do not cover. This might include new drugs under approval which could prove effective, but not approved by H&S as yet.

I think i'm almost done, except for a personal accident plan.

Thursday, September 1, 2016

Transactions for August 2016

Added another 100 ES3 shares. Happy to receive my first dividend payout from ES3 after restarting my portfolio. Even though it's only $4.20, it is actually quite motivating!

Slowly but surely, one minor minor step to more financial independence. :)


Dividends for August


By the way, there is an upcoming event for property, the Smart Expo.

If you are interested in building up a property portfolio overseas, do check it out if you have time!

Overseas property investment is fraught with lots of risks, including political, foreign exchange risks - but it's always good to get more knowledge anyway. :)

Tuesday, August 2, 2016

Transactions for July 2016

Going to start tracking my transactions and portfolio value after starting from scratch in June.

Transactions for the months of June and July:

As mentioned earlier, I would be performing monthly 'bites' into ETFs, 300 per month using SCB's low cost trading platform. The portfolio size is really.... 'pitiful'. But i am confident, slowly but steady, it will rise slowly back so that i can rely upon it for my eventual retirement!


On a slightly different note, i started a new blog to chronicle my renovation journey.

Reno Blog

Tuesday, July 12, 2016

Square 1

Haven't been blogging much, and i actually missed the Brexit drama, as I exited all my holdings prior to that.

I don't profess to have good foresight. I simply needed the money for the down-payment of my new home, so basically I have to sell off everything to come up with the cash requirements.

I got to say, it means i am starting all over again... no retirement portfolio, starting from scratch again. I consoled myself thinking that it's like giving up everything to be an entrepreneur, like Dividend Warrior selling off everything to open a tuition center, and rebuilding his portfolio from scratch.

At this time of uncertainty, why did i enter the property market? A lot of people are still very cautious, am i being foolish to be overweight on property?

(edit: and just nice one of my long time friend just posted about property http://investmentmoats.com/wealth-building-2/singapore-home-condo-landed-and-hdb-property-prices-grow-over-time/ and i quote "I came out of this exercise reinforced why wealth building through properties will always be a better option for many because of the low probability of people losing money.")

Prices have slightly cooled (though definitely nowhere near a crash have happened). It is a brand-new unit as it was unsold by the developer when it TOP 2 years back. To push sales this year, discount was given to buyers this year for them (or us) to bite. Effectively, I got it cheaper than those who purchased it earlier.

Also, I did not view it purely from an investment perspective as I am buying a home to live in. It really does check the boxes we are looking for for a home, being near good schools, quiet residential environment and being near MRT.

On the positive side, I am glad for this chance to clean up my portfolio as well. Going forward, i will be building up a pure ETF portfolio.

Starting from last month, I placed $300 into STI ETF (100 shares, with some leftover), and would be doing that every time I get my pay.
I did not choose to pay off the loan with the extra 300 as it would really not reduce it all that much, and building up some portfolio provides me with flexibility for liquidation next time.

In any case, it's back to square 1 from now on! After being debt free for some time, it's back to having a mountain of debt on my buttocks!


Sunday, July 3, 2016

Up, up, up and away


Been a furry of news these 2 weeks:

Singapore car park rates up $0.10 to $0.20, season parking up $15 to $25

Malls, office buildings set to charge higher parking fees

Cab firms hit by higher operating licence fees

Electricity tariffs to rise by 4.3%

Found a picture that adequately describes this:


I guess the most direct impact would be those driving cars (3 of the news pertains to car park charges). However, there would definitely knock-on effect to businesses - transportation costs etc. Rising costs would eventually be passed on back to the end-consumers.

There's a limit to how much expenses we can save (short of being a hermit) - look to ways to increase income to cope with the rising costs.

(1) Increase salary (easier stated than done sometimes)
(2) Start a 2nd line of income (part-time tuition maybe?)
(3) Passive income (what I am trying to do) - dividends, rental etc


Wednesday, June 22, 2016

Investors are speculating on Brexit

Did you get the oxymoron on my title?

I was engaged in a conversation recently with a financial advisor, and was asked if I am making bets on Brexit. The advisor said that a lot of investors are speculating on Brexit, and hoping to make a quick win over it.
I was scratching my head. Investors speculate?
Benjamin Graham in his book, 'The Intelligent Investor' defines an investment operation is one which, upon thorough analysis promises safety of principal and an adequate return. Operations not meeting these requirements are speculative. Betting on Brexit does not promise safety of principal. It's like going to casino, betting big or small. Same logic.

The financial advisor goes on to say, all the investors talked to also make decisions the same way. After doing research, the decisions are also made on gut-feel.

By definition, investors invest, and speculators speculate. It is worrying when people start listening to speculators thinking that they are investors. How can it be? The decisions made are based on 'gut-feel' - to me it is like gambling. How can we say someone who makes decision based on gut-feel as an investor, or a speculator as an investor?

Calling a speculator an investor is misleading, and if we listen to speculators thinking they are investors, I think we will be in for a surprise.


Friday, June 17, 2016

Lend me money?

So recently I managed to get a free copy of my credit bureau report. (if you don't know, if you apply for a new credit card, or have your credit limit re-assessed by your bank, you have a 30 days window period to log in and retrieve a free copy of your report)

So what does mine says?


So I was rated AA, with a 0.15% probability for default and a score of 1953. I was thinking, why was I not rated the maximum score of 2000?

So I read on, looks like one of the factors is that frequent/recent enquiries (in addition to default or slow payment) will affect the credit score.

I was never late on payment (always on Giro) so I wonder if it's the case if I applied for too many credit cards. I admit, I have a lot of cards, mostly for freebies + various discounts at various establishments. So let's see


23 enquiries, and 17 accounts. I guess that must be why.

With a good credit bureau rating, would you be willing to lend me money? Remember, there is only a 0.15% of me not paying you back :)

In any case, the Bureau also helpfully added that 1 way to improve credit score is to reduce unnecessary new credit card application. If you don't need, then don't apply, although I DO still keep apply for shiny new cards.

Friday, June 10, 2016

Waiting for my next pay (muses while showering)


No, it's not my pay day yet, although in all honesty, I AM indeed waiting for it. My current company bought out my notice period with my previous company - and in such cases, I need to pay my previous company compensation first (of 1 month + of my salary), and wait for the next payroll cycle in my current company before I get reimbursed.

In practical terms, it would mean I am out of 2 months of salary until this month end. So I do need to give myself a pat on my back that I managed to set aside emergency cash (as part of my resolution to get my finances back on track earlier) to sustain me for 2 months.

This also means I would get a bumper amount at the end of this month, definitely something to look forward to.

What about you? Do you look forward to pay day every month?
Any thoughts on how long you can sustain if you are without pay for 2 months?


Sunday, June 5, 2016

New job, new beginning

So I started with another company at the start of the month. Given the uncertainty surrounding my previous company, I decided to take the plunge and hunt around for a more secure job for my career. I did not wait for a severance package, because I think I would not be asked to go anytime soon, and I wasn't there for very long in the first place - hence my package (if any) won't be that large.

In any case, it gave me a good story to hop out, and I took the opportunity for an increment in base pay (I think it would take a few years in my ex-company for my pay to rise to my current now - I guess that's why they say if employees stay in the same company for too long, their pay would be below market value).


In all, it was pretty good, and I do hope I can stay sometime in my current company. I do not like unfamiliar environments, getting to know new people and trying to establish myself all over again.

A few things that struck me:
1. It's not good to be a job hopper, and there are certainly risks involved in changing jobs. On the flip side, there are opportunities involved. Always have a good story/rationale for what you do, and why a job switched is needed..
I was always told at my ex-company which was undergoing down-sizing to focus on what you can control. (I think they meant to focus on your work - but I took it to mean focus on getting another job which is within my control!) I rather be employed at my own terms, than be asked to leave at another's term!

2. I got my current job through my network (of course, I did go through interviews), so this highlights the importance of networking. Never burn bridges - you do not know when you will need to leverage on connections.

3. Have an adequate back-up cash reserves. I saw a few colleagues being let go over the past couple of months. Not too sure about their financial reserves - but I know some have a young family, some with mortgage commitments. It's important to have a buffer in case the severance package is not sufficient to tide over till the next job comes around.

So, with this new job and company, I hope to be here for good with them. :)

Wednesday, May 18, 2016

Prestige Life Rewards

I was introduced to this new and wonderful product by a Great Eastern Agent. Don't invest in property, invest in Prestige Life Rewards (PLR) by Great Eastern. This works like property investment, only better!

Wow - is it true?


Because this agent is a friend, I am open to hearing more, and I was promised an analysis between property investment and PLR. As I have a HDB, the comparison will be between the 2.

As I receive the analysis, I opened it up, and was immediately sold by the great benefits of this product. Let me share it with you.


Actually I was being sarcastic. These kind of "analysis" actually pisses me off more than anything.

The analysis is quite biased and did not present a balanced view of both products. There is only the supposedly good points of the product and the cons of property investment – to me, this is more a sales pitch than any fair analysis

For example, and just to name a few:

(1) There was mention of an upcoming oversupply of HDB flats. This failed to mention the governments intent of increasing population in Singapore.

(2) Failure to mention that we are in a rising interest rate environment, which would adversely affect the product (given the element of premium financing).

(3) ABSD was mentioned that is incurred in purchasing a property – a noticeable omission was the mention the equivalent distribution cost associated with purchasing the PLR?
This to me gives a very indication of where the 'advisor's' interest lies - whether in providing an unbiased comparison of 2 products, or only interested in talking up 1 particular tied product. I think the answer is very obvious.

Fortunately, I also received the Benefits Illustration. This is a product that has an element of premium financing. That is, I put in an initial $800,000 (based on my property value) for a total premium paid to Great Eastern of $2,392,912

So I compared the cash bonus (or passive income goes the sales pitch) vs the net rental


It is obvious to me that rental income from the HDB yields overall better passive income. And I need to remind myself that the passive income from PLR has the added advantage of leveraging, and the indicative rate is the higher end rate with 2% borrowing cost constant. How true is that? I will leave you to judge.

For transparency, I am using a monthly rental of $2,500 - given a 5 room HDB in Bukit Merah, rental increasing at 2% p.a, y.o.y. In URA's website, we can see that the rental at 2007 is approximate $2,000 vs $3,000 in 2016. Instead of the 4% increase, I used a more conservative rate of 2%.

The surrender value of the HDB (sale in this case), vs the PLR is quite different though as there is an element of leverage. If all goes well at the end of 40 years (at 4.75% rate by Great Eastern), the surrender value is $2,615,066. Would my HDB be worth the same 40 years later? Probably not. However, this is not an apple to apple comparison, given the leverage involved.

What would be more comparable is if I sold my HDB and purchased 2 properties with leverage. In that case, I am sure the pay-off changes again.

Is it a good product? Did I bite?

No - qualitatively, I doubt that the motivation of the 'advisor' is for my well-being. Quantitatively, PLR takes a higher risk profile as an asset and still fail to beat the passive income element.

I did not thank the agent for introducing this product as I felt like I wasted time analysing on an inferior product. Thinking back - perhaps I should thank the agent, because it gave me a topic to write upon.

It really drives home the point of how no one cares for your money more than yourself.


Saturday, April 30, 2016

Drinks and Party - what's your indulgence?

So it was TGIF yesterday, and after a hard and gruelling work at week, I think all of us can related to letting our hair down once the weekend rolls around.


However, due to time-table clashes, I was not able to join my friends for a Friday night of drinks yesterday, and from the group chat that I saw this morning, the bill per pax averages out to between $150 to $200. I do hang out with them sometimes, and I would say that's the average amount each shells out for a night of 'catching-up'.

As I started my trip back to financial independence last year, I have used YNAB, and my monthly allocation to personal dining out is only around 200-400 per month. I would say 1 night out with them would blow my entire month's budget. So in that sense, I have now preferred to have cheaper alternatives like house parties etc, where you can still drink (if you want to), but at a much cheaper rate. [I hope they do not read this entry!]

I think everyone have their own indulgence of choice. I use to have more indulgences I think, but I have learnt to cut down some to get my budget in order.

Café-hopping - those Instagram worthy moments with oh-so-lovely food. I know there are some people who do café-hopping every weekend


Fancy restaurants - A friend of mine don't drink tap water at restaurants, and always order sparkling. That's at least $6 just for plain water at meals.

Transport - There are some who swears by taxi every where they travel. Each trip could be around $20 - 1 month? around $1,000 I guess.

Shopping - enough said.

Hobbies - Some folks travel once every two months.

Of course, I have the largest indulgence to support, my car. I guess that's why some things have to go!

I won't call it a sacrifice - some things I do not really enjoy. I like hawker food over cafes anyway, kopitiam kopi to fancy Americano. I do not think my quality of life suffered, and I do feel that my money is spent on more meaningful things (like my retirement fund)

I guess, as long as 1 has the budget, and has a well worked out resource allocation plan, one should feel free to indulge in whatever they want to. After all, life is short. If you do not have an interest or two to indulge in - what's the point in living?

Spend on yourself in the present, but don't forget to spend on yourself for the future. :)

Tuesday, March 1, 2016

Update Feb 2016

In addition to recording my transactions, I also decided to track down on a monthly basis, how much passive income i receive from dividends


Total of $815 for the month of February. Given that i only hold 15,000 STI ETF shares, seems like February is a good income month for me.
The yield of the ETF is around 3.5% to 4% at this current price now.

Also elected to receive dividends in the form of scrips for Frasers Commercial Trust since i do not need cash at the moment, so might as well reinvest it back in.

Added 500 shares to my STI ETF for this month, at a price of $2.65. A lot of people are avoiding the markets given the volatility, but my thinking is that if i am comfortable buying in at $3.30, i should be even more comfortable buying in at a lower price.

Gonna be adding positions on a regular basis going forward!

Sunday, February 21, 2016

Windfall

Well, sad to say, i did not turn into an instant millionaire following my previous post - 12-million Hong Bao draw.

I did have a consolation 'prize', as my company announced the year end incentive award (or bonus). So with the windfall (well, being able to keep my job is already good enough for me!), any bonus award can really be considered a bonus.

As with any windfall received, adequate planning is required, otherwise it will all be squandered away. Many stories on the net about people spending their inheritance within a month!

So i took the opportunity to plan out what to do with the excess amount that i will receive, and came to the conclusion - money will never be enough. No matter how much i have, i will be able to find ways to fill it up.


I will sock away 40% to my household account, and build up my emergency cash. 

The emergency cash is in line with my resolution for 2016. See Goals 2016. Given the current economic climate recently, i guess it is better to be conservative on my part to increase my buffer.

I will also take the opportunity to replace my fixed assets, namely my laptop, which has been with me for the past 6 years. 
Other non-savings expenses include allocating the bonus to my annual travel plans, as well as other expenses like giving a bonus to my family as well.

My regrets in coming up with this budget? I did not manage to allocate to 2 categories:
(1) Increasing my personal war-chest. I guess that would come with my monthly salary instead.
(2) Accruing for the tax on this bonus. Again, it would have to come from my regular budget.

What about you? I hope you have had a windfall recently as well. :) and please do share with me how you intend to allocate them.